《最优解人生》是比尔·帕金斯的作品,当前资源标题记录的电子书格式为 PDF / ePub / mobi / azw3。这页先帮助读者确认书籍身份、内容主线和阅读预期,再核对实际文件状态。
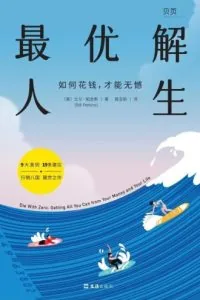
基本信息与出版版本
| 书名 | 最优解人生 |
|---|---|
| 作者 | 比尔·帕金斯 |
| 类别 | 个人理财 / 生活哲学 / 心理学 |
| 出版社 | 中信出版社 |
| ISBN | 9787521752174 |
| 电子书格式 | PDF / ePub / mobi / azw3 |
不同版本的出版社、译者、封面和排版可能存在差异;页数如果来源不足,本页不强行补写。实际电子书版本请以下载后的文件内容为准。
这本书主要讲什么
《最优解人生》(Die With Zero: Getting All You Can from Your Money and Your Life)是由美国对冲基金经理、职业扑克手比尔·帕金斯所著的现象级畅销书。
中文书评
《最优解人生》是一本会让人重新审视金钱用途的生活哲学类作品。它并不是一本单纯教人如何投资、储蓄或积累财富的理财书,而是试图回答一个更根本的问题:我们花费几十年时间赚钱,最终到底希望用这些钱换来什么。比尔·帕金斯以对冲基金经理和职业扑克玩家的经历为基础,将金融思维与人生规划结合起来,提出了一个与传统“尽可能多存钱”的观念不同的方向:财富的价值不在于账户数字不断增加,而在于它是否帮助一个人在有限的人生时间里获得更多真正重要的体验。
作品的背景建立在现代社会普遍存在的一种矛盾之上。很多人习惯把人生划分为“年轻时努力工作,中年积累财富,退休后再享受生活”,但现实中,时间、健康和金钱并不会永远同时充足。比尔·帕金斯观察到,人们经常为了一个遥远的未来牺牲当下,却忽略了一些体验具有明显的时间窗口。例如,年轻时进行长途旅行、挑战高强度活动,和朋友共同创造回忆,这些事情到了年纪更大时,即使拥有更多金钱,也可能因为身体条件、家庭责任或精力变化而无法复制。书中提出的“记忆红利”概念,就是强调一次有价值的经历并不会随着结束而消失,而会在未来很多年持续产生情感价值。
作品的核心主题并不是鼓励毫无计划地消费,而是重新定义“理性使用金钱”。比尔·帕金斯认为,钱本身不是人生目标,而是一种交换工具,可以换取时间、关系、体验和选择权。他提出根据人生阶段安排资源:年轻时利用健康优势获得难以替代的经历,中年时利用收入购买时间,把精力留给家庭和重要关系,年长后则更加关注舒适、陪伴以及财富如何产生实际影响。这种观点挑战了传统财富观,因为它关注的不只是“拥有多少”,而是“这些拥有是否在正确的时间发挥作用”。
书中的人物分析主要围绕作者本人展开。比尔·帕金斯并不是以传统理财专家的身份出现,而是带着高风险行业从业者的经验来讨论人生决策。他曾经面对过财富增长、风险控制以及概率判断等问题,因此书中的很多观点带有明显的投资思维:人生也是一个资源配置问题,每一次选择都意味着放弃其他可能性。他并没有塑造一个完美的人生样本,而是在描述一个不断调整策略的人。例如,他关注的不只是如何避免贫穷,也关注那些已经拥有一定经济基础的人,是否因为过度谨慎而错过了真正想要的生活。
这本书最大的优点,是它提出的问题足够尖锐。很多理财书强调积累,却很少讨论积累之后如何使用。《最优解人生》让读者重新思考储蓄背后的目的,也提醒人们不要把未来的不确定性当成永远推迟生活的理由。书中的观点容易理解,案例和生活场景结合较多,因此即使没有专业金融背景的读者,也能感受到其中的现实意义。
不过,作品也存在一定局限。它的理念更适合已经具备基本经济安全感的人群,对于收入不稳定、债务压力较大或缺少长期保障的人来说,“尽可能充分利用财富”的建议需要更加谨慎地理解。书中部分观点依赖个人情况,例如预期寿命、收入增长、家庭责任和风险承受能力都会影响实际执行效果。如果机械套用“花掉更多钱去体验人生”,反而可能带来新的压力。因此,这本书更适合作为一种思考框架,而不是一套适用于所有人的财务公式。 《最优解人生》适合那些长期忙于工作、习惯延迟满足、正在思考财富意义的人阅读,也适合处在人生转折阶段,希望重新安排时间和金钱关系的读者。它尤其适合已经开始储蓄投资,但发现自己只是在追逐数字增长,却没有认真规划生活体验的人。
总体来看,《最优解人生》的价值不在于提供一个简单答案,而在于改变人们看待财富的角度。它提醒读者,金钱最终需要服务于人生,而不是让人生永远围绕积累金钱展开。比尔·帕金斯提出的“用财富换取更完整的人生”这一理念并非适用于所有情况,但它确实提供了一种值得思考的视角:真正需要优化的,也许不是账户里的数字,而是有限时间里的生活质量。
English Review
Die With Zero: Getting All You Can from Your Money and Your Life is a thought-provoking work that challenges the traditional way people think about wealth, saving, and personal success. Rather than presenting itself as a conventional personal finance guide focused on investment returns or building a larger net worth, Bill Perkins’ book asks a more fundamental question: what is the purpose of earning money if we never fully use it to create a meaningful life?
Drawing from his experience as a hedge fund manager and professional poker player, Perkins combines financial thinking with life philosophy to argue that money should be treated as a tool for maximizing valuable experiences rather than simply accumulating assets. The background of the book comes from a common conflict in modern life. Many people follow a familiar pattern: work hard when young, save aggressively during adulthood, and postpone enjoyment until retirement.
Perkins argues that this approach ignores the fact that people have three changing resources throughout life: time, health, and money. These resources rarely peak at the same moment. A person may have plenty of energy and curiosity when young but limited financial resources; later they may have more money but less physical ability or freedom. The book explores how decisions about spending should consider timing, because some experiences lose value when delayed for too long.
The central theme of Die With Zero is that wealth should be converted into meaningful experiences, relationships, and memories while a person is still able to enjoy them. Perkins introduces ideas such as “memory dividends,” suggesting that certain experiences continue to provide emotional value long after they happen. A family trip, a major adventure, learning a new skill, or spending meaningful time with loved ones may continue influencing a person’s happiness for decades. In this view, money that remains unused forever may represent opportunities that were never taken.
However, the book is not simply an argument for reckless spending. Perkins does not suggest abandoning financial responsibility. Instead, he argues for intentional allocation of resources. He encourages readers to think about different stages of life and match spending decisions with those stages. Younger people may benefit from experiences that require energy and physical ability. Middle-aged people may benefit from using money to buy back time, such as reducing unnecessary tasks and creating more space for family. Older individuals may focus more on comfort, generosity, and meaningful connections.
The main figure in the book is Perkins himself. His background shapes the way he approaches life decisions. As someone familiar with risk, probability, and financial markets, he views life as a series of choices involving limited resources. His perspective is different from many traditional financial writers because he is not only concerned with avoiding financial failure. He is equally concerned with another type of failure: reaching the end of life with security but with too many unrealized experiences.
His arguments often reflect the mindset of someone who understands that every decision has an opportunity cost. One of the book’s strongest qualities is its ability to challenge assumptions that many readers rarely question. Personal finance discussions often focus on saving more, investing better, and increasing wealth. Perkins shifts attention toward the purpose behind those actions. His writing encourages readers to examine whether their financial habits are actually supporting the life they want to live.
The ideas are presented in a practical and accessible way, making the book understandable even for readers without a financial background. The book also has limitations. Its philosophy works best for people who already have a reasonable level of financial stability. For individuals struggling with debt, unpredictable income, or insufficient savings, the idea of intentionally reducing wealth may feel unrealistic or risky. In addition, many recommendations depend heavily on personal circumstances, including health, family obligations, income level, and risk tolerance.
The book provides a valuable framework for thinking, but it should not be treated as a universal financial formula. Die With Zero is especially suitable for readers who feel trapped in a cycle of working, saving, and postponing life. It will appeal to people reconsidering their priorities, planning major life transitions, or wondering whether their financial choices reflect their actual values. It is also useful for those who have achieved some financial progress but want to think more carefully about how money can improve their everyday life.
Overall, Die With Zero is valuable because it changes the question people ask about wealth. Instead of asking only how much money they can accumulate, it encourages them to consider how effectively that money is being used. Bill Perkins does not provide a simple answer for everyone, and some of his ideas require careful adjustment depending on individual circumstances. Still, the book offers a meaningful perspective: the ultimate goal of financial planning may not be owning the largest possible fortune, but using available resources to build a life that feels complete.
我的阅读笔记
从现有资料看,它最值得关注的是:《最优解人生》(Die With Zero: Getting All You Can from Your Money and Your Life)是由美国对冲基金经理、职业扑克手比尔·帕金斯所著的现象级畅销书。读《最优解人生》时,可以先抓住作者比尔·帕金斯怎样设置背景、人物目标和主要冲突,再看这些部分如何导向主题。
第二个重点是目录、前言和章节安排。如果它能继续推动人物选择、冲突升级和主题回响,这本书就更适合细读;如果只是信息并列,阅读价值会弱一些。
我觉得最值得看的地方
我觉得最值得看的地方,是它围绕“《最优解人生》(Die With Zero: Getting All You Can from Your Money and Your Life)是由美国对冲基金经理、职业扑克手比尔·帕金斯所著的现象级畅销书”展开的部分。这一点能帮助读者进入作品真正的矛盾,而不是只停在题材表面。
如果你关注个人理财 / 生活哲学 / 心理学,可以读完一章后用一句话写下这一章的观点,再决定是否继续精读。这样读完后留下的不是零散印象,而是对人物、冲突和主题的清楚判断。
与同类书有什么区别
读《最优解人生》之前,先判断它属于个人理财 / 生活哲学 / 心理学里的哪一种:是入门科普、方法书、教材,还是案例型读物。这个判断比只看格式更有用。
第一次读重点看什么
第一次读《最优解人生》,先看它在回答什么问题,再看作者怎么展开。可以先抓这两点:《最优解人生》(Die With Zero: Getting All You Can from Your Money and Your Life)是由美国对冲基金经理、职业扑克手比尔·帕金斯所著的现象级畅销书;再结合目录判断自己要不要细读。
- 《最优解人生》(Die With Zero: Getting All You Can from Your Money and Your Life)是由美国对冲基金经理、职业扑克手比尔·帕金斯所著的现象级畅销书
哪些人适合读,哪些人可能不适合
如果你正在找《最优解人生》电子版,可以先确认 PDF / ePub / mobi / azw3 这些格式是否够用。想判断内容值不值得读,就看它在个人理财 / 生活哲学 / 心理学里解决的是哪类问题。
如果你需要的是完整纸质版校勘、特定译本差异或严格学术引用,请优先核对出版社、图书馆或 ISBN 书目系统;如果只是先找电子版阅读,则重点看格式、作者和版本字段是否符合自己的需求。
比尔·帕金斯和这本书的关系
比尔·帕金斯和《最优解人生》的关系,不只是“这本书的作者”这么简单。读这本书时,更值得看的是作者怎样处理个人理财 / 生活哲学 / 心理学方向里的核心问题,以及这些观点为什么会被整理成一本书。
如果你想评估这本书值不值得读,不要只看作者名气。更实用的办法是看作者提出的问题、使用的材料,以及这些内容能不能形成稳定的主题推进。
常见问题
《最优解人生》主要讲什么?
《最优解人生》主要围绕“《最优解人生》(Die With Zero: Getting All You Can from Your Money and Your Life)是由美国对冲基金经理、职业扑克手比尔·帕金斯所著的现象级畅销书”展开。这个入口决定了作品的背景、冲突和主题方向。
《最优解人生》适合什么人读?
它适合愿意围绕《最优解人生》的主题、人物关系和结构推进慢慢读下去的读者。如果只想要非常轻快、直接、低门槛的阅读体验,可能不一定合适。
读《最优解人生》最该关注哪一点?
读《最优解人生》时,建议先看它提出了什么问题,再看作者比尔·帕金斯如何展开。真正决定阅读价值的,是人物选择、冲突发展和主题回响是否能互相支撑。
《最优解人生》电子书有哪些格式?
当前记录的格式为 PDF / ePub / mobi / azw3。实际可用文件、排版和版本信息,以页面底部资源模块和下载后的文件为准。
电子书格式与获取说明
当前页面记录《最优解人生》的电子书格式为 PDF / ePub / mobi / azw3。不同来源的电子书在排版、封面、译名和文件质量上可能会有差异,下载后请以实际文件信息为准。
